Umbrella liability · Price check
One accident, one lawsuit, and the gap is paid from your savings.
Your auto and home limits are lower than most people assume. Everything above them is personal, and it is collected from what you own and what you earn.
A serious at-fault accident is not a fender bender. It is a hospital, a lost income claim, a lawyer and a number that starts at six figures. Your auto policy pays to its limit and stops. The rest does not disappear; it follows you, into savings, into equity, into future earnings, which is why an umbrella sits on top and costs less than most people expect.
Does this sound like your umbrella liability?
- You do not know what your auto liability limit actually is.
- There is a pool, a dog, a boat or a rental property in your life.
- A young driver has joined the household.
- You assumed your home and auto limits were far higher than they are.
- You have been told an umbrella is only for wealthy households.
The gap is not abstract
A household with a house, two cars and a retirement account has something worth suing for. That is the exposure an umbrella covers.
It sits above auto and home liability and picks up where those limits end, usually in million-dollar steps.
The risks people underestimate are in their own backyard
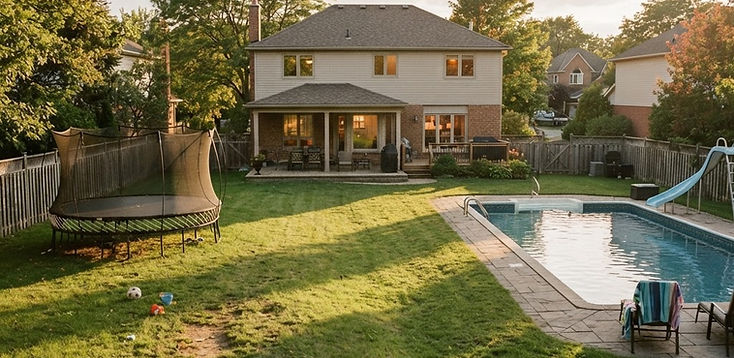
A pool, a trampoline, a dog with a bite history, a boat, a rental property, a teenager with a licence: each of these raises the ceiling on what a claim can cost.
Most of these claims are not filed by strangers. They are filed by guests, neighbours and their insurers.
“You insure the house. Almost nobody insures what happens after the house is not enough.”
It only works if the underlying limits are right
Carriers require a minimum auto and home liability limit before they will issue an umbrella. If yours is below that, the umbrella has a hole at the bottom.
The price check includes those limits, because the fix is often adjusting the base policy rather than buying more.
One short form, and a licensed agent takes it from there.
Tell us your state. Your inquiry is forwarded to one licensed insurance agency licensed in that state, which will contact you about umbrella liability. No obligation.
What we check before we call you back
This is not a form that disappears into a queue. It is a working list an agent goes through with you on the call for umbrella liability.
- Auto and home liability limits against umbrella requirements
- Excess liability limits of $1M to $5M
- Whether rentals, watercraft and recreational vehicles are included
- Uninsured motorist stacked above your auto limits
- The actual premium for the additional protection
One short conversation establishes the ceiling you currently have and what raising it costs. Most households discover the number is smaller than they feared and the exposure was larger.