Boat & watercraft · Price check
Your homeowners policy covers the boat in the driveway. Not the water it is sitting on.
Watercraft are excluded from homeowners policies above a very small size and horsepower. On the lake, you are either separately insured or uninsured.
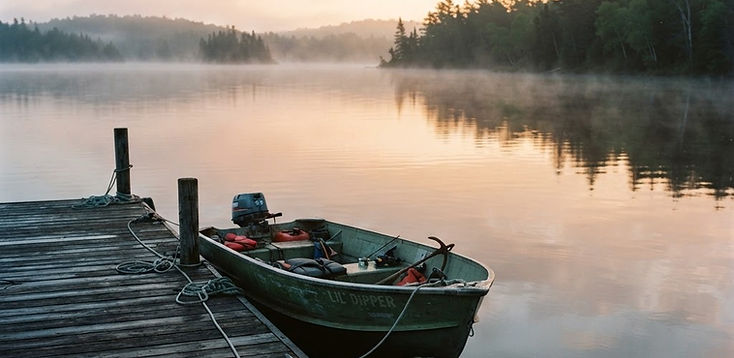
The boat sits in the driveway for eight months and it feels like part of the house. Then it is on the water with four people aboard, a fuel line, a propeller and a hull that costs more to replace than most cars. At that moment the homeowners policy has already stepped aside: size and horsepower limits, no liability on the water, no towing, no fuel spill.
Does this sound like your boat & watercraft?
- You are not sure whether your boat is still covered by the home policy.
- The marina is asking for a certificate of insurance.
- Your last quote was based on a hull value that is not what the boat is worth.
- Towing, trailer or equipment theft has never been discussed with you.
- You have two watercraft and one policy.
Where the homeowners policy stops
Small outboards sometimes stay on the home policy. Above that threshold, you need a watercraft policy for hull, liability and everything the lake can do to you.
The gap shows up as a denied liability claim, which is the expensive kind.
Agreed value, not depreciation
A hull claim paid at depreciated value on a fifteen-year-old boat rarely covers the replacement you actually want.
Agreed value coverage fixes the number at the start, and it is the first thing worth comparing between quotes.
“The lake does not read your homeowners policy. It reads your watercraft policy.”
The costs nobody thinks about until the season starts
On-water towing, fuel spill liability, trailer coverage, winter storage and equipment theft are separate line items, and they are where cheap policies get thin.
If you keep the boat at a marina, the slip agreement usually requires liability coverage on file before the season opens.
One short form, and a licensed agent takes it from there.
Tell us your state. Your inquiry is forwarded to one licensed insurance agency licensed in that state, which will contact you about boat & watercraft. No obligation.
What we check before we call you back
This is not a form that disappears into a queue. It is a working list an agent goes through with you on the call for boat & watercraft.
- Hull value on an agreed value basis
- Watercraft liability limits
- On-water towing and assistance
- Trailer, equipment and personal effects
- Lay-up period and winter storage conditions
Tell an agent what you have, where it is kept and how it is used. You get a real number for the season, not a bundle guess.